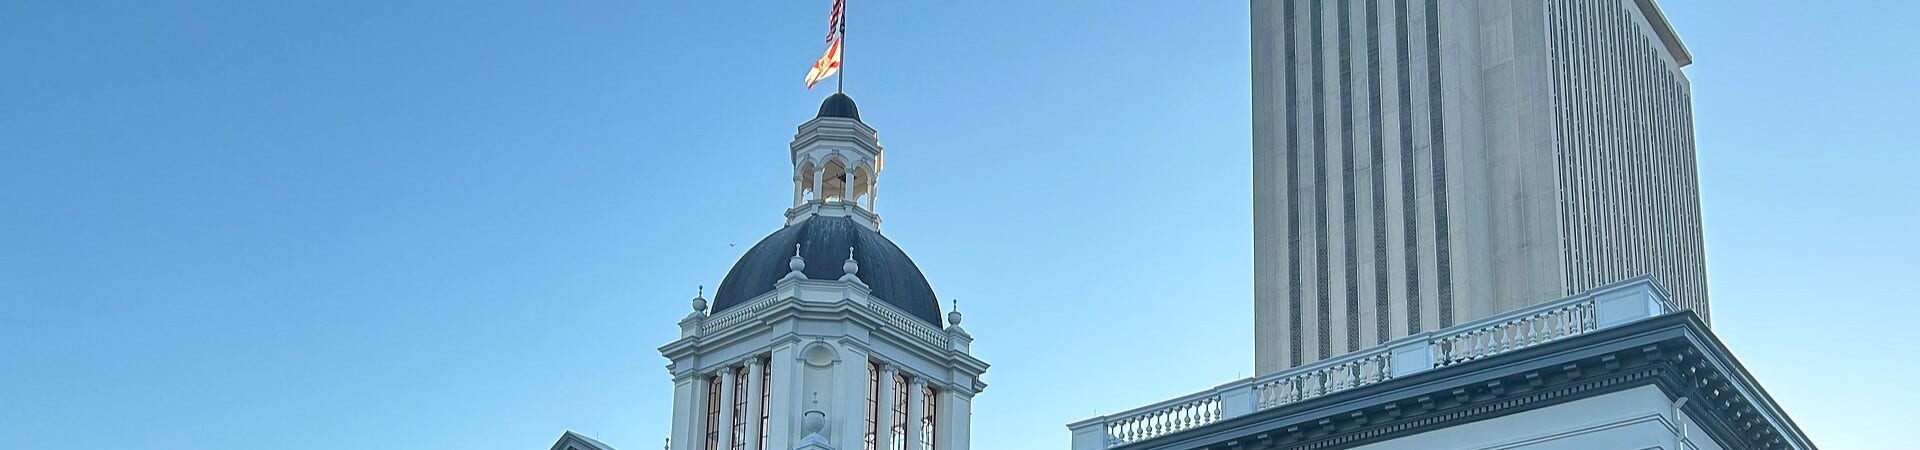
Voters approved the property tax amendment on November 3 with about 62% of the vote. For landlords and rental investors, the change that matters is not the bigger homestead exemption. It is a lower cap on how fast a rental property's taxable value can rise.
It Passed, With Room to Spare
Florida voters approved Amendment 3 on November 3, 2026. Results compiled by Decision Desk HQ show 4,922,400 yes votes to 3,019,415 no votes, or 61.98% in favor, clearing the 60% a constitutional amendment needs in Florida. The other two amendments on the ballot failed: Amendment 1, on the state's rainy-day fund, drew about 41%, and Amendment 2, an agricultural equipment exemption, reached 58%, just short of the threshold, according to WUSF.
Support was strong in Newkirk's Northwest Florida markets. Yes led by roughly 32 points in Escambia County and 46 points in Santa Rosa County.
The short answer for investors: Amendment 3 takes effect January 1, 2027. It raises the homestead exemption for owner-occupied homes and, separately, cuts the annual cap on assessment increases for rentals, second homes, and commercial property from 10% to 5%. Rental property does not qualify for the homestead exemption, so the lower cap is the part that changes a landlord's tax bill.
What Changes on January 1, 2027
The Florida Chamber of Commerce's summary of the amendment lays out four pieces:
- Homestead exemption. For non-school taxes, the exemption rises to $150,000 beginning with the 2027 tax roll and to $250,000 in 2028, with inflation adjustments after that. The existing $25,000 exemption continues to apply to school taxes.
- Non-homestead assessment cap. Annual assessment increases on commercial, industrial, and rental property are capped at 5% for non-school levies, down from 10%, beginning in 2027.
- New-resident rule. People who become Florida residents after January 1, 2027 must be residents for five years before qualifying for the larger exemption. Counties and cities can shorten that period with a two-thirds vote.
- Limits on how property tax revenue is spent. County and city property tax revenue is directed to public safety, schools, infrastructure, natural resources, debt service, employee retirement benefits, and operations, with other spending allowed unless state law prohibits it.
Why the 5% Cap Is the Real Story for Landlords
The cap limits how much a property's assessed value can rise in one year, even when its market value jumps more. Cutting it from 10% to 5% slows how quickly a rental's tax bill can climb during a strong market. Before the vote, Bay News 9 reported on a Largo landlord with five rental homes who estimated roughly $80,000 in avoided tax increases on one property over time under the lower cap.
Two limits are worth understanding. First, the cap applies to non-school levies, so the school portion of the bill is not covered by the change. Second, the cap restrains assessed value, not the tax rate. The Chamber's summary notes that counties and cities keep their millage authority within existing constitutional limits, which means a local government can still raise its rate.
The Pressure on Local Budgets
The state's Revenue Estimating Conference projects that Amendment 3 will reduce local property tax revenue by about $4.9 billion in fiscal year 2027-28 and $8.7 billion in 2028-29, with a recurring impact near $11.8 billion a year. Those estimates assume flat property values and unchanged millage rates.
That gap has to be made up somewhere: higher millage rates, new fees and assessments, or cuts to services. Owners of rental and commercial property should watch all three, because a new fee lands on an investment property the same way a higher tax bill does. The debate was not one-sided even among supporters. Senate President Ben Albritton voted to put the measure on the ballot and later argued it would hurt rural communities with limited resources, while Gov. Ron DeSantis backed a yes vote and said the measure did not go far enough.
For background on how the amendment was structured, see our earlier explainer, Florida's Amendment 3 Property Tax Overhaul: What Rental Investors Need to Know.
What Investors Should Do Now
- Re-run your 2027 numbers. Model holding costs with a 5% annual cap on assessment growth for non-school taxes instead of 10%.
- Watch your county and city budget hearings. Millage rates and new fees are where the revenue shortfall is most likely to show up.
- Check the timing on new purchases. A sale resets a property's assessed value to market value, so the cap protects you going forward from the purchase year, not from the prior owner's assessment.
- If you are relocating to Florida, note the five-year residency rule before counting on the larger homestead exemption for a primary residence.
The Investor Takeaway
Amendment 3 is a real benefit for long-term owners of rental and commercial property, because it halves the rate at which assessed value can grow each year. It is not a guarantee of lower bills. Local governments facing billions in lost revenue still control millage rates and fees, so the smart move is to budget for the lower cap and keep a close eye on what your county and city do next.
Work With Newkirk
If you own or are considering rental or commercial property in Pensacola, Gulf Breeze, Milton, Pace, Daytona Beach, Ormond Beach, Port Orange, or Palm Coast, a Newkirk Investments agent can help you model how the new assessment cap and local budget decisions affect your holding costs. Call 386-290-5356 or email hello@newkirk-investments.com.
Sources
- Decision Desk HQ — 2026 Florida Amendment 3 results (updated Nov. 7, 2026)
- WUSF — Florida voters approve Amendment 3 property tax reduction (Nov. 3, 2026)
- Florida Chamber of Commerce — Florida's 2026 Property Tax Amendment 3 (updated Nov. 9, 2026)
- Bay News 9 — Amendment 3 Could Offer Tax Savings for Investors That Own Rental Properties (Sept. 30, 2026)


Responses